7 Real Drivers of Your Monthly General Liability Insurance Cost
Jeffrey CarvalhoCA License #0783367
· 11 min read
Last Updated: November 12, 2026
Quick Summary
General liability insurance cost most small businesses between $40 and $100 per month, with the average landing near $45 monthly for small operations. Your actual general liability insurance cost depends on your industry, revenue, and claims history, and 22% of small businesses pay under $30 monthly.
- A $1M/$2M policy typically runs $350 to $1,000 annually, or $29 to $83 monthly.
- Your industry risk profile drives the biggest swing in what you pay.
- A single paid claim can raise your premium at renewal for three to five years.
- Raising your deductible lowers your monthly installment but increases out-of-pocket claim costs.
- At $45 monthly, a decade of premiums totals $5,400, less than one covered claim.
Table of Contents
- What Most Small Businesses Actually Pay Each Month
- General Liability Insurance Cost for $1 Million in Coverage
- The Factors That Move Your Monthly Premium Up or Down
- General Liability Insurance for a Small Business: Where the Money Goes
- General Liability Insurance for a Cleaning Business
- Using a General Liability Insurance Cost Calculator
- Real Claims That Show What Your Premium Buys
- Request a Free Quote and Lock In Your Real Number
- Frequently Asked Questions
What Most Small Businesses Actually Pay Each Month
General liability insurance costs most small businesses between $40 and $100 per month, according to Homebase's 2026 small business insurance cost guide. The average lands near $45 monthly for small operations, per Insureon's general liability cost data, though your actual number depends on your industry, revenue, and claims history.
That spread matters. Insureon also reports that 22% of small businesses pay under $30 monthly, while 41% fall in the $30 to $60 band.
Below, we break down the seven real drivers behind your quote, so you can see where your money goes before you ever call an agent.
General Liability Insurance Cost for $1 Million in Coverage
Premiums for a $1 million per-occurrence policy with a $2 million aggregate limit vary widely by business. For current pricing specific to your operations, request a quote from Farmers Insurance.
Here is how the general liability insurance cost breaks down by coverage tier:
| Coverage Level | Typical Annual Premium | Monthly Equivalent | Best For |
|---|---|---|---|
| $500K per occurrence | $300 - $600 | $25 - $50 | Low-risk office work |
| $1M / $2M aggregate | $350 - $1,000 | $29 - $83 | Most small businesses |
| $2M / $4M aggregate | $700 - $1,800 | $58 - $150 | Client contracts requiring higher limits |
| $5M umbrella added | $1,500 - $4,000 | $125 - $333 | Landlords, property managers |
The aggregate limit caps total payouts across all claims in a policy year. A single slip-and-fall settlement can consume a $500K limit fast, which is why most commercial leases and client contracts require the $1M tier.
The Factors That Move Your Monthly Premium Up or Down
Underwriting looks at your business classification first, then layers in location, payroll, revenue, and claims history. What follows is how each lever actually moves the monthly number, so you can see which ones you can pull before you ever call an agent.
Your industry risk profile drives the biggest swing. Trades with power tools, ladders, and client premises access pay more than desk-based consultants. Classification codes matter here: two businesses with the same revenue can be priced apart because the carrier's class code assigns a different base rate per $1,000 of payroll or per $1,000 of revenue.
Revenue and payroll set the exposure base. Higher gross sales mean higher potential claims, so carriers price accordingly. Many small policies are rated per $1,000 of payroll for service businesses and per $1,000 of revenue for retail and contracting operations. A 20% jump in payroll does not always mean a 20% jump in premium, because minimum premiums and class modifiers absorb part of the change, but the direction is reliable.
Location-based rates reflect local litigation trends and repair costs. Premiums can vary by where you operate, since carriers file rates by territory. Carriers file rates by territory, so moving a service area across a county line can change your quote even when nothing else about the business changes.
Claims history is the strongest single predictor. A single paid claim can raise your premium at renewal for three to five years, and carriers often apply a claims modifier that follows the policy rather than the owner. The HHS study of nursing home liability costs in Georgia documented a 123% rise in liability costs over its study period, showing how fast a state's legal climate can shift premiums even for operators with clean records.
Coverage limit and deductible are the two levers you control at the point of quote. The deductible works in the opposite direction and deserves its own look.
How Your Deductible Changes the Monthly Number
Raising your deductible can lower your monthly installment. You absorb more of each claim before the insurer pays. The trade-off is cash-flow math, not just a discount.
A $500 deductible keeps premiums higher but limits out-of-pocket exposure. A $2,500 deductible cuts the monthly bill, yet a single property damage claim now costs you $2,500 before coverage kicks in.
Deductibles also interact with the claim type. Many general liability policies apply the deductible per occurrence, and defense costs may sit inside or outside the limit depending on the form. A business that chooses a $2,500 deductible to save $150 a year can find itself writing that check on a $4,000 property damage claim where the insurer would otherwise have handled the whole thing. The right choice depends on your cash reserves: businesses with steady cash flow often take the higher deductible and bank the savings, while startups with thin margins usually keep the deductible low.
Bundling and payment plan round out the levers.
General Liability Insurance for a Small Business: Where the Money Goes
Your premium buys four core protections. Third-party bodily injury covers medical costs when someone is hurt on your premises or by your work. Property damage pays to repair or replace client property you damage.
Personal and advertising injury covers claims like libel, slander, and copyright infringement in your marketing. Legal defense costs sit outside the settlement, and defense alone can run tens of thousands before a case resolves.
What most guides miss is that defense costs often exceed the settlement itself. Carriers price that risk into every quote, which is why even a clean claims history does not guarantee the lowest rate.
General Liability Insurance for a Cleaning Business
Cleaning businesses pay more than office-based operations because crews work inside client buildings, handle chemicals, and move through spaces they do not control.
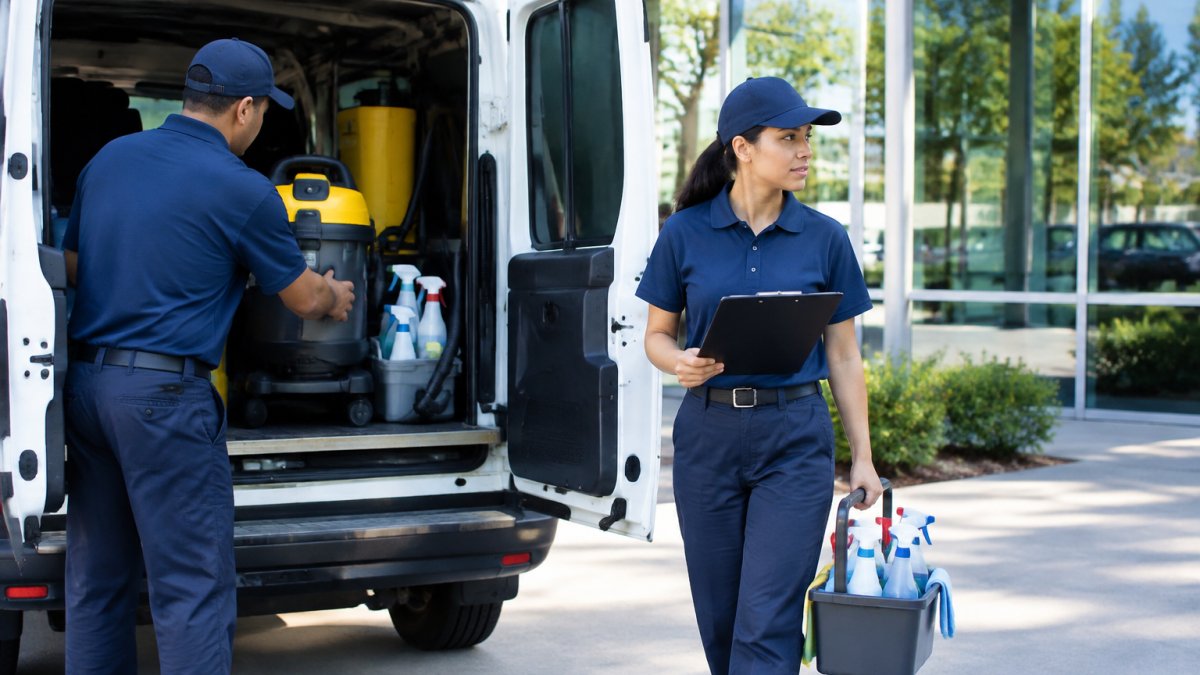
The main exposures are straightforward. A crew knocks over a client's display case. A floor treatment damages hardwood. Someone slips on a wet surface your team just mopped.
Watch out: skipping coverage because a client "probably won't sue" leaves you personally liable for property damage your crew causes. Most commercial cleaning contracts require a certificate of insurance before you set foot on site.
Using a General Liability Insurance Cost Calculator
A general liability insurance cost calculator gives you a ballpark in about two minutes. You enter your industry, revenue, payroll, location, and coverage limit, and the tool returns an estimated monthly range.
Treat that number as a starting point, not a quote. NerdWallet notes that published averages do not reflect individual risk profiles, since underwriting weighs factors a calculator cannot capture.
What the calculator misses:
- Your specific claims history and any prior losses
- Subcontractor arrangements and certificates of insurance
- Contractual requirements from landlords or clients
- Whether bundling with property or workers' comp changes your total
At Farmers Insurance, we run your details through multiple carriers, including Farmers, Mercury, and Progressive, so you see real quotes rather than estimates.
Real Claims That Show What Your Premium Buys
Abstract coverage descriptions do not answer the monthly-price question. The useful comparison is what a claim actually costs against what you pay each month.
Slip-and-fall at a restaurant. A patron slips near a wet floor sign and breaks a wrist. Your $1M policy covers it after the deductible, and your premium rises at renewal.
Landscaper property damage. A trimmer throws debris through a client's window and damages a $4,000 piece of furniture. If the policy carries a $2,500 deductible, you pay that amount and the insurer pays the remaining $1,500 plus any defense costs. This is the scenario where a high deductible hurts: the savings from a lower monthly bill can vanish on a single small claim.
Advertising injury. A retailer reuses a stock photo in a social media campaign without the license. The photographer's agency sends a demand for $12,000. Personal and advertising injury coverage responds, including defense, and the claim resolves without a lawsuit. Many owners assume this exposure only applies to marketing firms; it applies to any business that publishes content.
Third-party bodily injury away from your premises. A cleaning crew mops a client's lobby, a visitor slips on the wet floor, and the medical bills and settlement reach $30,000. The claim lands on the cleaning company's policy, not the client's, because the injury arose from the crew's work. This is the exposure that makes certificates of insurance a contract requirement for most commercial cleaning work.
The ROI framing. One covered claim typically exceeds a decade of premiums. At $45 monthly, a decade of premiums is $5,400. The restaurant claim above is more than 15 times that figure. The point is not that every business will face an $85,000 claim; it is that the monthly price is small relative to the tail of outcomes the policy absorbs. A business that goes claim-free for a decade still bought something real: the ability to absorb a single bad event without wiping out operating cash or personal savings.
What the scenarios do not cover. General liability does not pay for damage to your own property, employee injuries, or professional mistakes. Those need property, workers' compensation, and professional liability policies respectively. A claim in one of those categories will be denied under a general liability policy, which is why the monthly number should be read alongside the rest of your coverage stack rather than in isolation.
Request a Free Quote and Lock In Your Real Number
Published averages tell you what businesses like yours pay. They cannot tell you what you will pay.
The gap between the $45 monthly average and your actual quote comes down to your classification, claims history, and coverage limits. Farmers Insurance has over 30 years of experience, and we work as a broker with access to multiple carriers to find coverage that fits your budget.
We also offer bundling options for personal auto and homeowners coverage to help save on insurance costs.
Get started with Farmers Insurance and turn an estimate into a real number you can plan around.
Most business owners wait until a contract deadline forces the conversation. Start earlier, and you give yourself room to compare coverage scope, adjust your deductible, and bundle policies before renewal pressure hits. Farmers Insurance can walk you through a risk assessment and quote comparison in a single call, with customized coverage options built around how your business actually operates.
Frequently Asked Questions
How much does $1,000,000 in general liability insurance cost per month?
Published averages put the general liability insurance cost for $1 million in coverage in the range of roughly $40 to $100 per month for many small businesses. Insureon reports an average of $45 per month. Your actual rate depends on your industry, revenue, location, and claims history, so treat these as starting points rather than a quote.
What factors affect monthly general liability insurance costs?
Underwriting looks at your business classification and industry risk profile first, then business size, annual revenue, location-based rates, and claims history. Your chosen policy limit, aggregate limit, and deductible also move the number. A consultant working from a home office typically pays less than a contractor with job-site exposure.
How much is general liability insurance for a cleaning business?
Cleaning businesses can face different risk exposures because crews work inside client property and handle chemicals. The exact premium depends on payroll, number of locations serviced, and coverage limits. A general liability insurance cost calculator can give you a working estimate, but a broker quote based on your actual operations is more accurate.
How can I estimate my general liability insurance cost?
Start with a general liability insurance cost calculator to get a ballpark based on industry, revenue, and location. Then compare that number against published averages like Insureon's $45 per month. The estimate narrows once you factor in your deductible and coverage scope. A free quote from an agent who can shop multiple carriers will give you the real monthly installment figure.